Annuity sales red flags are easiest to spot when you watch the conversation in order: the invitation, the pitch, the paperwork and the close. Each stage has its own pressure moves, and each has a question that tells you quickly whether the person across the table is working for your plan or for their commission.
This article follows that order. It covers what happens before you sign. If you are already past that point, the last section is for you.
Why annuities attract pushy selling in the first place
Most annuities are sold by agents or advisors who are paid a commission by the insurance company, usually built into the product rather than billed to you separately. That is a legal and common arrangement, and plenty of agents are honest within it. The problem is the incentive: the commission is often larger on products with longer surrender periods or more complicated features, and the agent only gets paid if you sign.
Annuities are also hard to compare. Payout rates, caps, participation rates, riders and surrender schedules differ from one contract to the next, so a buyer who is short on time has to take the salesperson’s summary on trust. Pressure tactics work best when the buyer cannot check the details independently, and that describes most annuity pitches.
Pressure is a flag even when the product is a good one. A suitable annuity will still be suitable next week, after you have read the contract and asked a second professional.
Question to hold in mind throughout: “How are you paid if I buy this?” Ask it early and watch whether the answer is direct. A fair answer names the commission or tells you where to find it in the disclosure documents.
The free-dinner seminar and other invitations built to create pressure
The first contact often arrives as a mailer for a free steak dinner, a “retirement income workshop” or a postcard promising to “protect your savings from the next downturn.” The meal is not the offer. The event is a lead-generation tool, and the real purpose is to book private follow-up appointments with attendees.
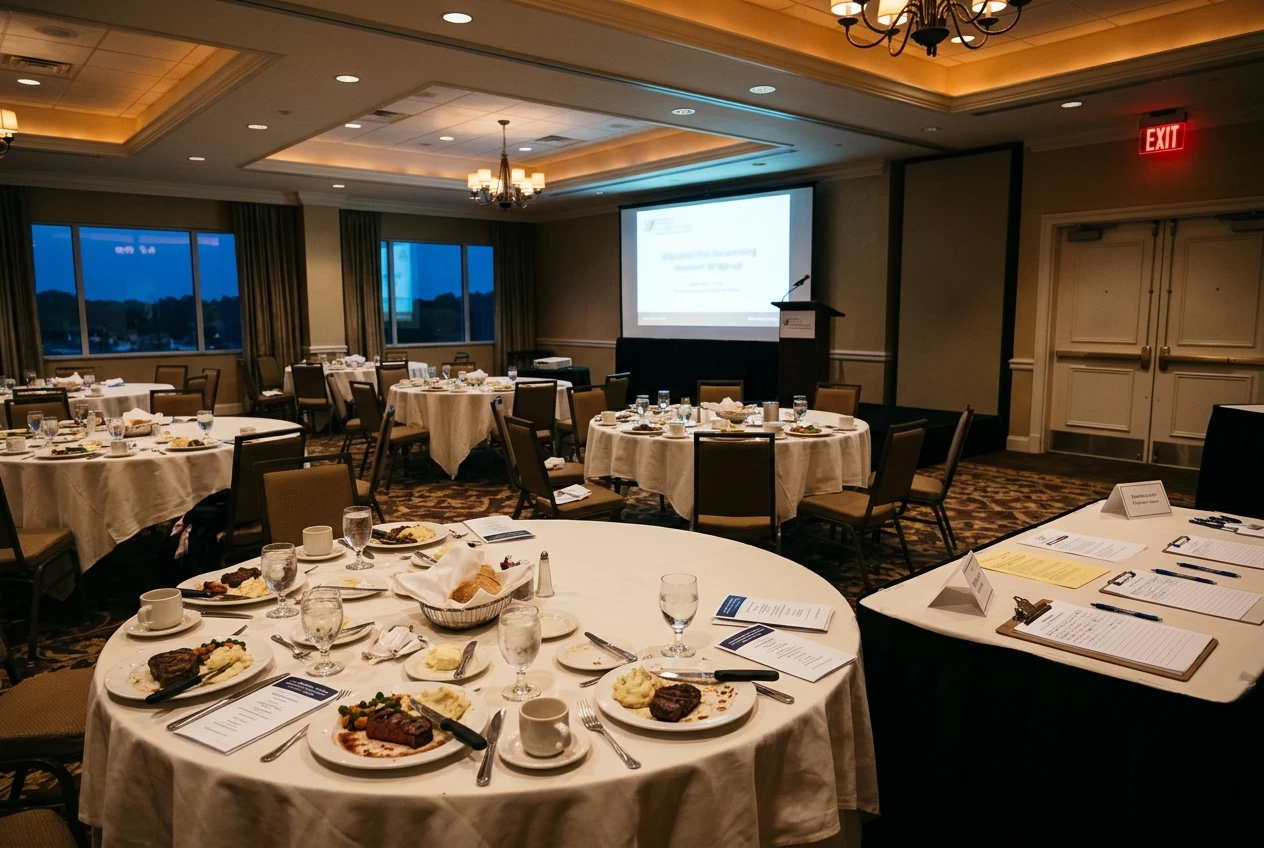
Watch for these features of the invitation and the event:
- A title that promises education, but a room that ends in a sign-up sheet. If the speaker asks everyone to schedule a “personal review” before leaving, the seminar was a sales funnel.
- Scarcity. “Only a few one-on-one slots left this week” is a scheduling device, not a fact about your finances.
- A request to bring statements. Asking you to bring recent account statements to a first meeting lets the salesperson see exactly what money is available before you have decided anything.
- Fear as the opening. Slides about market crashes, inflation or running out of money are designed to make you feel behind. The product appears afterward as the relief.
You can attend a free dinner and leave without booking anything. The question to ask at this stage is “Is this event an educational presentation or a sales presentation, and will I be asked to schedule an appointment?” If the host dodges that, you have your answer.
Phrases that signal a pitch is about commission, not your plan
Once you are in a one-on-one meeting, listen for language that skips over your situation. A sound recommendation starts with your income needs, your other assets, your tax position and your health. A commission-driven one starts with the product.
Phrases worth noting:
- “Guaranteed income with no risk.” Guarantees in an annuity depend on the claims-paying ability of the insurer and on the contract terms. Every product carries some trade-off, such as limited access to your money, a cap on gains or fees for added features.
- “You can’t lose money.” This may be true of the principal in certain contracts under certain conditions, but it ignores inflation, surrender charges and what you give up in liquidity.
- “This is the best product on the market.” No product is best without reference to the buyer. If the agent has not asked about your spouse, your expenses or your other income, the claim is unsupported.
- “This offer expires Friday.” Insurers do change rates, but a sales deadline that is shorter than the time you need to read a contract is a tactic.
- “Your banker or accountant doesn’t need to be involved.” A good recommendation survives a second opinion.
Question to ask: “What about my situation makes this product a better fit than the alternatives, and which alternatives did you consider?” A strong answer refers to specifics you gave earlier. A weak one repeats the product’s features.
Vague answers on surrender charges, fees and caps
Surrender charges are the penalty for withdrawing more than the contract allows during the surrender period. They are the single most important cost to understand before buying, because they determine how locked in you are. Fees, riders and caps shape what you actually earn.
A salesperson who is working for you will put these numbers on the table early. Be wary when you hear:
- “The surrender charge is small, and you’ll never use it.” Ask for the schedule in writing, year by year, and for the length of the surrender period.
- “There are no fees.” Many fixed products do not charge an explicit annual fee, but the cost shows up elsewhere: in caps, spreads, participation rates or rider charges. Variable products usually list several layers of fees. “No fees” is rarely a complete statement.
- “The cap is just for now.” In indexed products, caps and participation rates can often be changed by the insurer after the initial period, within contract limits. Ask what the minimum guaranteed cap is, not the current one.
- “I’ll get you that in the paperwork.” If an agent cannot give a number now, ask for the page of the contract or disclosure where it appears.
Questions to ask: “What is the full surrender schedule, and how much can I withdraw each year without a charge?” and “What can the insurer change after I buy, and what is the worst case in the contract?”
Being urged to cash out other accounts or replace an existing annuity
Some pitches depend on moving money you already have. Two versions deserve extra caution.
Cashing out other accounts. An agent may suggest liquidating an IRA, a 401(k), certificates of deposit or investments to fund the annuity. Withdrawals from tax-deferred accounts can trigger income tax, and possibly penalties if you are under 59½. Moving the money by direct transfer or rollover may avoid some of that, but the right method depends on the account. If the agent has not mentioned the tax consequences, they have skipped the part most likely to cost you.
Replacing an annuity you already own. Swapping one annuity for another can be legitimate, and a tax-free exchange under Section 1035 exists for that purpose. But a replacement often starts a new surrender period, may cost you benefits you have already built up and pays the agent a fresh commission. Most states require replacement disclosures for this reason. Be especially skeptical of the pitch “your old annuity is outdated, this one is better,” unless the agent can list, line by line, what you lose and gain.
Questions to ask: “What will this cost me in taxes and surrender charges, in dollars, if I move this money?” and “What benefits in my current contract would I give up, and does a new surrender period begin?” For a broader look at what goes wrong after purchase, see the piece on common mistakes with annuities in retirement.
Paperwork moves: blank fields, rushed signatures and unexplained riders
The application is where a vague pitch becomes a binding contract, and a few habits at this stage should stop you.
- Blank fields. Never sign an application with empty sections that “we’ll fill in later.” Check every answer about income, net worth, age, existing coverage and your goals for the money. Wrong entries can make an unsuitable product look suitable.
- Pre-filled answers you did not give. If the form says you have a high risk tolerance or do not need access to this money, and you said no such thing, correct it before signing.
- A stack of signature pages. If the agent flips to the signature tabs and skips the content, ask to slow down. You are entitled to read before signing.
- Riders presented as free extras. Income, death benefit and long-term care riders usually carry a cost, and they come with conditions. The agent should be able to say what each rider costs, when it applies and how it can be exercised. If an optional benefit is part of the pitch, read the explanation first, such as the page on the long term care rider.
- Pressure to sign today. Contracts do not expire at the end of a meeting. You can take the paperwork home.
Question to ask: “Can I take the full contract and disclosure documents home and return the application after I’ve reviewed them?” A salesperson who agrees is confident in the product. One who resists is telling you something.
Questions to ask before you sign, and how to read the answers
Bring a short list and write down the answers. Ask for anything important in writing. These questions cover the main risks:
- How are you paid, and does it vary by product? A good answer is specific. A bad one is “don’t worry about that.”
- What is the surrender period and charge schedule? You want year-by-year numbers.
- What are all the fees, including rider costs? Ask for a total in dollars on a sample amount, not just percentages.
- What can the insurer change after I buy? Look for rates, caps and participation rates, and for the guaranteed minimums.
- What happens to the money if I die early, or if my spouse outlives me? The answer should cover beneficiaries and any payout options.
- How would I get at my money in an emergency? Ask about free withdrawal limits, and about waivers for illness or nursing care.
- What other options did you consider for me, and why not those? Fixed, indexed, immediate and deferred products solve different problems, and so do non-annuity options.
- How long is the free-look period? Many states give a window after delivery to cancel for a refund, but the length varies by state and product, so ask for it in writing.
Reading the answers is simpler than it sounds. Direct answers with numbers and document references are good signs. Answers that redirect to the benefits, promise to follow up later or treat the question as an insult are red flags. Check the agent’s license with your state insurance department, and consider having a fee-only advisor, who does not earn commission on the sale, look at the contract before you commit. For a side-by-side method, the guide on how to compare different annuity products goes through the features that matter.
What to do if you already signed and now have doubts
Act quickly, because the best options are time-limited.
- Check the free-look period. The contract or its cover letter should state it. If you are still inside it, you can usually cancel and request your premium back. Send the cancellation in writing, by a method that gives you proof of delivery, and keep copies.
- Gather every document. That means the application, the contract, the illustration, the disclosures, any replacement forms and notes from your meetings. Compare what the agent said with what the paperwork says.
- Ask for a written explanation. Contact the insurer and ask for the surrender schedule, current caps and rates and the cost of every rider on your contract.
- Get an independent review. A fee-only advisor or a licensed professional with no stake in the product can tell you whether it fits your plan.
- Know where to complain. State insurance departments take complaints about agents and insurers, and securities regulators handle variable annuities. If you believe you were misled, the page on legal recourse in annuity disputes outlines the routes available.
If the free-look period has passed, do not assume you are stuck. Surrender charges often decline over time, and some contracts allow a yearly penalty-free withdrawal. Knowing the exact numbers is the first step to deciding whether to stay or leave.
Check your quote against the list
If you have an annuity quote or proposal on your desk, go through it against the questions above. Mark any answer that was vague, any number you were never given in writing and any moment you were hurried. Then read the guide on how to compare different annuity products to see how your quote stacks up against the alternatives before you decide.